

Introduction
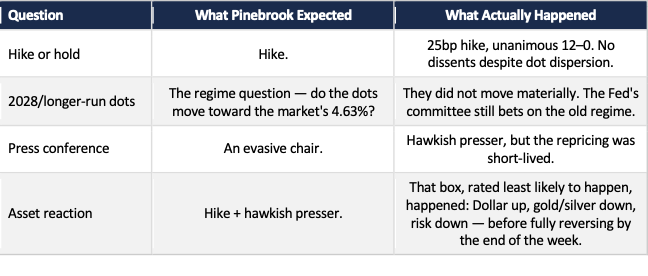
Last week’s FOMC policy rate decision and Fed Chair Warsh’s subsequent press conference are now in the rear-view mirror. After a bit of flirting with near-term volatility, the market has moved on. So should we, after a parsing of the receipts.
The pre-summer thesis that led up to the above was laid out back in May, in Cruel Summer, with a projected increase in U.S. 10-year nominal yields because of:
Broad price pressures that were moving up. ✅
A reacceleration of the labor market. ✅
Labor market price pressures found in healthcare benefits, not wages. ✅
Rising earnings projections that were symptomatic of an expanding economy. ✅
The sequencing of the Fed’s policy stance from pause to neutral to tightening over the course of the summer, validated by Chair Warsh in Jackson Hole in late August. ✅
These ideas were further examined a few weeks later in The Calm Before on May 30, where August was highlighted as a window of vulnerability and of maximum stress in the rates market.
Off by two weeks, but close enough is still a win.
While the semi trade was flagged as stretched at 4–5 sigma, the L needs to be taken on not having flagged that as a sell signal. It was indeed a sell, and a big miss here. ❌
The semi unwind was called a rotation on June 8th: money moving between sectors rather than what it actually was, which the start of a multiple compression.
The bond market broke bad, but did so by an order of magnitude greater than what these pages expected.
The Cruel Summer framework and its follow-ups correctly called the Fed’s path from pause to neutral to tightening, along with rising earnings expectations.
What it missed was drawing out the implication of its own rate call on equities.
The multiple did exactly what the rate path predicted it would do.
While it’s early days, the data footprint is pointing toward an avoidance of the inflationary regime shift, the real Baba Yaga these pages have spent the summer watching for.
Now that the world’s most important FOMC meeting has come and gone without the world ending, it’s time to take stock of where we are in the cycle as the market front-runs the pricing of risk assets into 2027.
I. The Tape Today
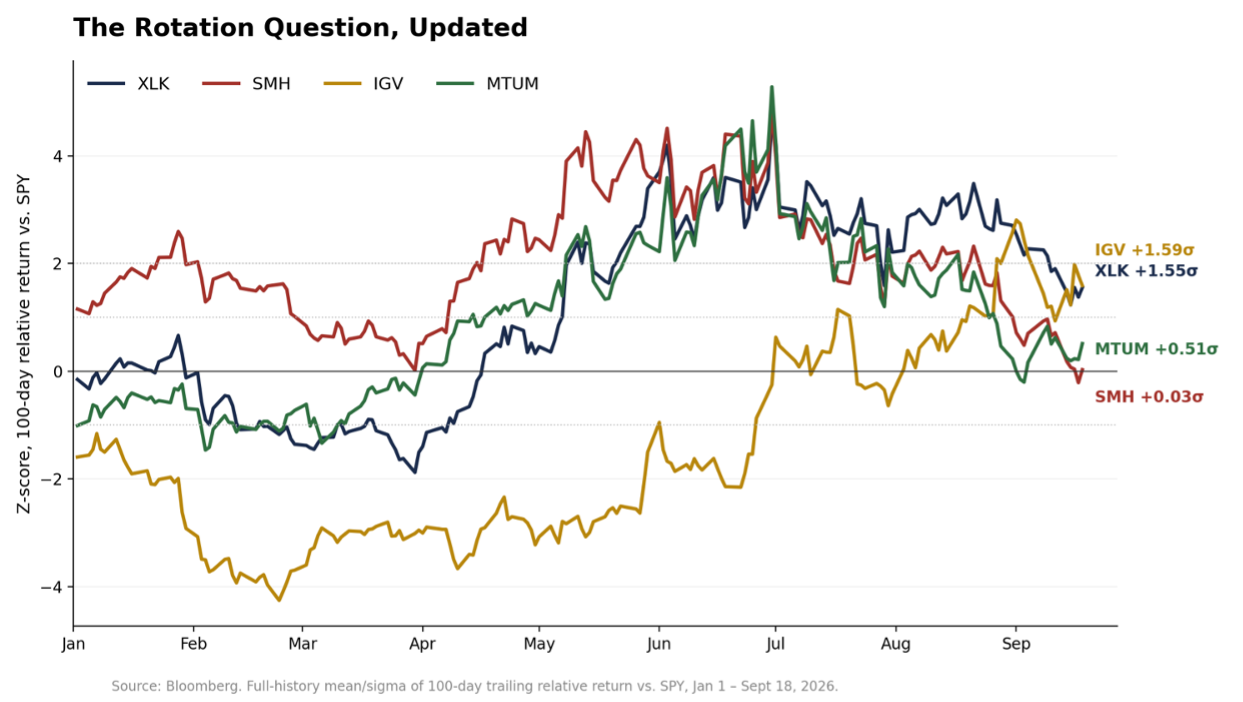
SMH and MTUM are fully normalized, at 0.03σ and 0.51σ, respectively.
Whatever was left of the semis overextension from summer is gone.
XLK cooled from 2.14σ to 1.55σ but didn’t fully reset.
IGV: software is now the most stretched name of the four, peaking near 2σ on the FOMC day itself and still elevated at 1.59σ.
Hardware/semis have normalized while software has gotten more extended over the same window.
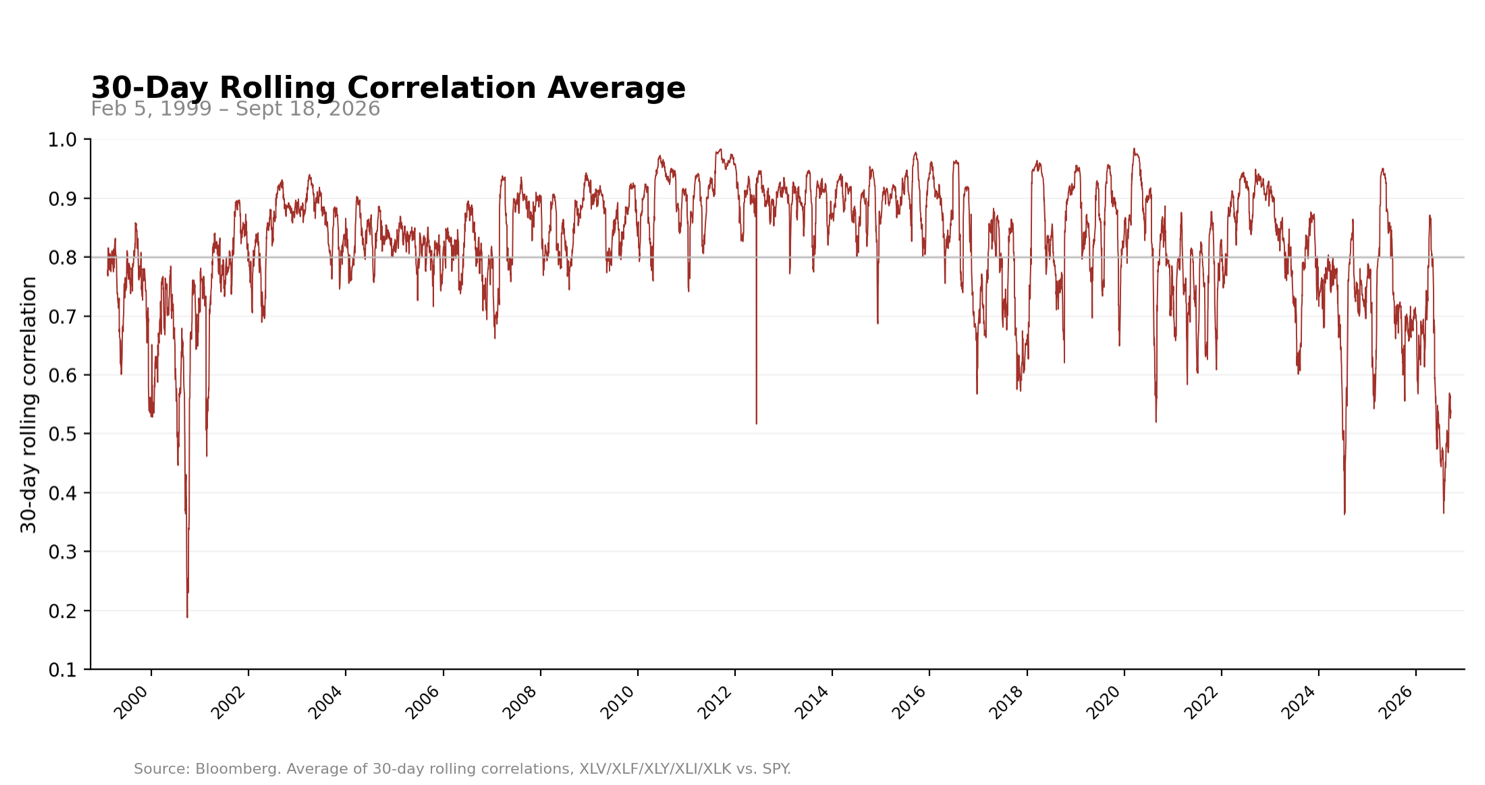
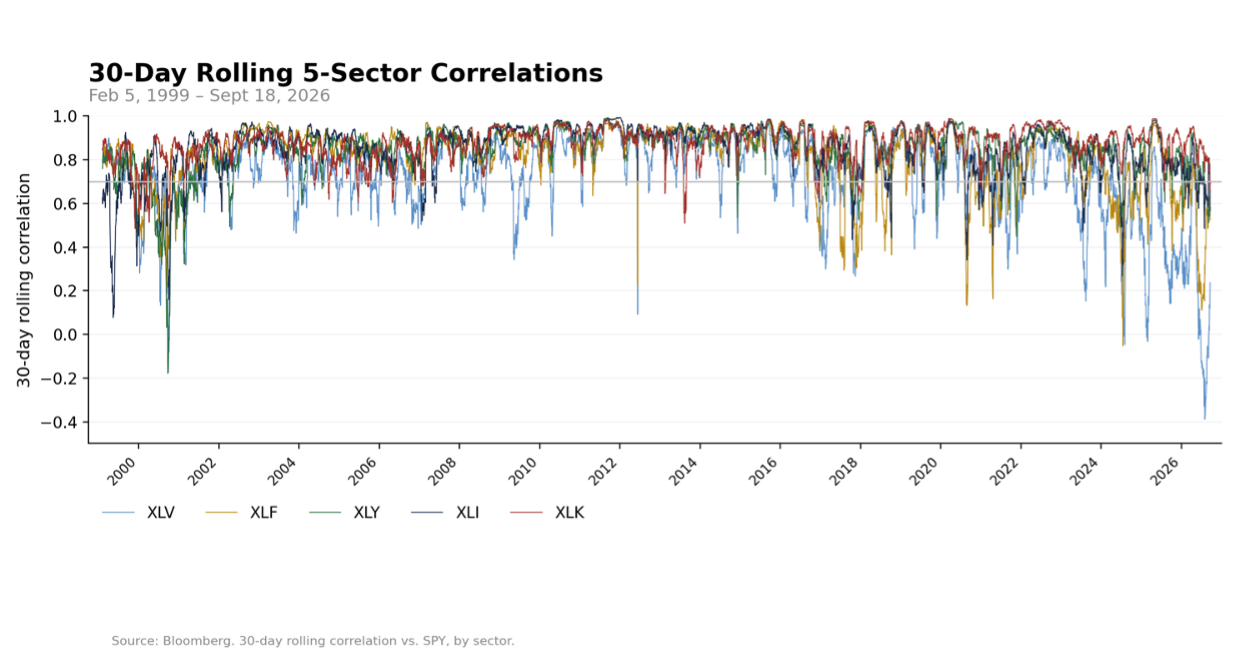
A sectoral anomaly was flagged in the June 8 note: healthcare. By July 31st, healthcare’s correlation to the index had fallen to -0.389, the most negative reading in its entire history back to 1999.
What that divergence represented was a crowded trade with money moving into healthcare as a defensive, rate-sensitive parking spot during the tech unwind and extreme enough to push correlation to its lowest reading on record.
A trade stretched that far eventually runs out of new money, and that’s what started happening the moment the correlation bottomed.
From the July 31st trough, XLV’s correlation climbed in a long, almost uninterrupted grind — to -0.21 by mid-August, to zero on September 8th, and to +0.237 by September 18th.
Healthcare took the entire round trip alone and has now rejoined the group it broke away from.
A single sector trading with a correlation this negative to its own index is a crowded trade that usually unwinds.
Based on the evidence above, the hardware-and-momentum leg of the summer rotation is over. A narrower one in software specifically looks like it may just be getting started.